Mortgage Rate Buydowns: How Fullerton Buyers Are Paying Less Than 7% in 2026
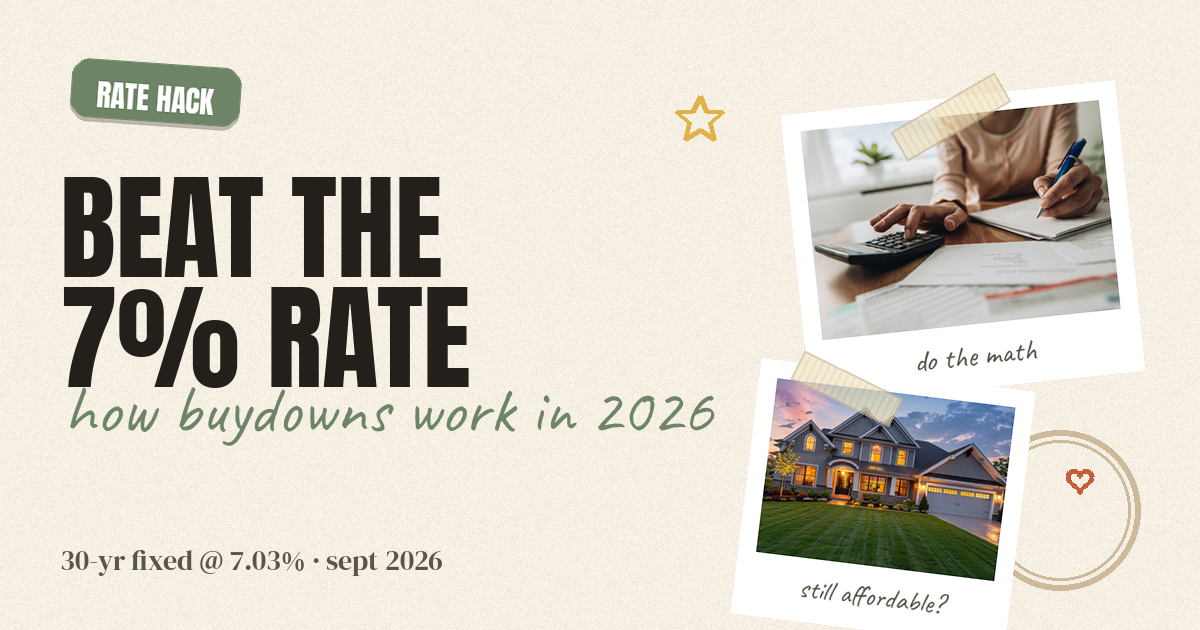
The 30-year fixed mortgage rate hit 7.03% in late September 2026, according to Freddie Mac — up from 6.30% a year ago. For Fullerton buyers staring at seven-figure price tags, that number feels like a wall.
It's not. There's a door in the wall, and it's called a rate buydown. Here's how it works, what it actually costs, and how buyers in this market are getting sellers to foot the bill.
What a mortgage rate buydown actually is
A buydown is simple: money paid upfront to temporarily lower your interest rate. The most common structure right now is the 2-1 buydown:
- Year 1: your rate is 2% below the note rate
- Year 2: your rate is 1% below the note rate
- Year 3+: you pay the full note rate
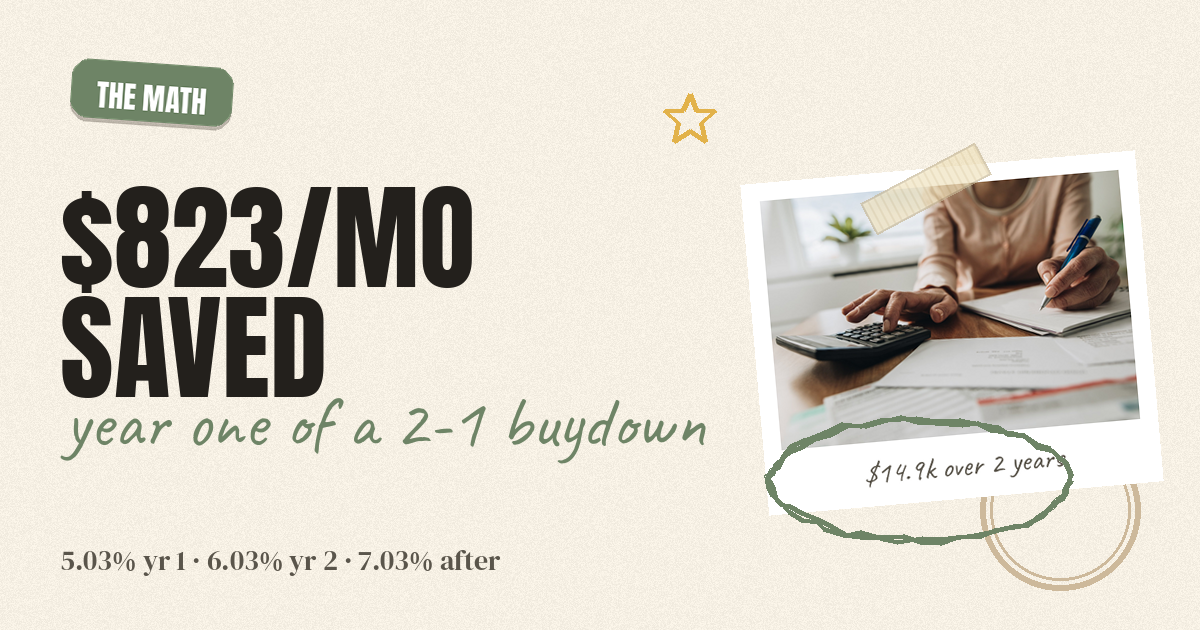
So if your note rate is 7.03%, you pay roughly 5.03% in year one and 6.03% in year two. There's also the 1-0 buydown (1% off for one year, cheaper) and permanent buydowns (discount points that lower the rate for the life of the loan).
The buydown money sits in an escrow account and covers the difference each month. If you refinance or sell before the buydown period ends, the unused balance typically comes back to you.
The math: what a buydown saves on a Fullerton home
Let's run real numbers. Say you buy at $800,000 with 20% down — a $640,000 loan at 7.03%:
- No buydown: about $4,271/month principal & interest
- Year 1 with 2-1 buydown (5.03%): about $3,448/month — $823/month saved
- Year 2 with 2-1 buydown (6.03%): about $3,850/month — $421/month saved
That's roughly $14,900 in payment savings over the first two years — breathing room while you wait for a refinance window if rates ease.
The buyer's-market secret: make the seller pay for it
Here's where 2026's market dynamics change everything. In a seller's market, no seller would pay for your buydown. In this market, with homes sitting 40+ days and price cuts spreading, seller-paid buydowns are one of the most common concessions in negotiation.
Why sellers love it: a buydown credit costs them less than a price reduction, and unlike a price cut, it doesn't drag down the recorded sale price.
Why buyers love it: it attacks the actual problem — the monthly payment — instead of just trimming the price.
How to ask: instead of offering $25,000 under asking on a stale listing, offer closer to asking but request a 2-1 buydown credit at closing. Many sellers will take that deal when they'd reject the price cut.
Buydown vs. price reduction: which wins?
It depends on your situation:
- Buydown wins if the monthly payment is your constraint, you might refinance in a few years, or the seller won't budge on price but will concede on credits.
- Price reduction wins if you're putting less down, you plan to stay long-term past the buydown period, or property taxes are a concern (lower price = lower tax basis).
Often the best deals combine both: a modest price cut plus a buydown credit on a home that's been sitting 60+ days.
Who should (and shouldn't) use a buydown
Great fit: buyers whose income will grow, anyone expecting to refinance within 2–3 years, and buyers using seller concessions in a buyer's market.
Think twice: if you're stretching so thin that you can't afford the year-3 payment, a buydown is a band-aid, not a solution. Make sure you're comfortable at the full note rate long-term.
The bottom line
Waiting for rates to drop is a strategy — it's just a passive one. Buydowns let you buy the home you want now, pay less while the market is in your favor, and refinance later if the opportunity comes. In a buyer's market, the seller might even pay for the privilege.
Want me to run buydown numbers on a real Fullerton listing? I'll model the 2-1, the 1-0, and the straight price cut side by side so you can see exactly which saves you more. DM me "HOME" or call/text (714) 732-1860.
Ruben Martinez | Redfin Agent | DRE #01946610 | Serving Fullerton & North OC
Categories
Recent Posts